Financial Crises, Part III: The Rise and Fall of France's Mississippi Bubble
Author: Self-Control
Reviewers: Guanfu · Juntian
Correction: In the previous installment, we said that John Law solved the government’s long-standing debt problem by replacing metal currency with paper money. That was not the case. His measures merely eased some of the pressure, and we have corrected the account below.
In the previous installment, we described how John Law replaced metal currency with paper money and tightly controlled the bank’s reserves to maintain public confidence. He used tax measures to promote the new notes, helping to revive the French economy. Paper money was easy to carry and inexpensive to use, which also helped the economy grow quickly. For the second step of his plan, Law established the Mississippi Company. In 1717, the French government issued a charter authorizing him to form a commercial enterprise to develop the supposedly rich mineral resources of the Mississippi River basin in North America. The company held a monopoly on trade throughout the river’s vast watershed, hence the name Mississippi Company. Its initial capital was 100 million livres, divided into 200,000 shares worth 500 livres each. Investors could buy shares at face value with treasury notes. Soon after its founding, the company gained additional privileges, including the right to collect taxes and mint coins. Government backing, coupled with a steady stream of reports about precious-metal deposits throughout the Mississippi basin, sent demand for its shares soaring. Since investors could exchange treasury notes for shares at the same face value, government debt also continued to fall. As demand grew, the government instructed the General Bank, by then renamed the Royal Bank, to issue another one billion livres in banknotes. This sudden surge in liquidity began to inflate a stock-market bubble. Money was now driving share prices: as vast sums entered the market, prices climbed with them. The Mississippi Company, whose prospects seemed excellent at the time, could use its stock to absorb surplus money and keep the government’s large-scale note issuance from immediately causing severe inflation. This mechanism became one of the pillars supporting the bubble’s later expansion.
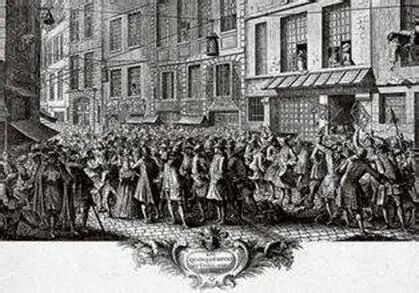
In 1917, two large new share issues by the Mississippi Company sent the bubble into a period of rapid expansion. Early that year, the French government granted the company additional monopolies on trade with the East Indies, China, the islands of the South Pacific, and territories administered by the French East India Company. The company then issued 50,000 new shares to expand its capital and promised generous dividends. Investors could once again purchase the new stock at face value with treasury notes whose market price was steadily falling. On that basis, each share reportedly offered a return as high as 120%. Those extraordinary returns, combined with the government-controlled General Bank’s continued expansion of the banknote supply, further inflamed the public’s enthusiasm for stock-market speculation. Old and new shares alike rose rapidly, and the bubble swelled. Then, in 1719, the Mississippi Company set out to eliminate the government’s debt burden altogether by issuing another 300,000 shares at 5,000 livres each, for a total of 1.5 billion livres. All of them could be purchased at face value with treasury notes. To support this audacious plan, the General Bank issued another 1.5 billion livres in banknotes with government authorization, driving the share price still higher. The entire market was now in the grip of an investment frenzy. Mississippi Company shares sometimes jumped 10 to 20 percent in a matter of hours. The flood of money also fueled severe inflation and soaring consumer prices. Ever more cash had to pour into the stock market to support the growing number of shares and keep their prices from falling. Yet that money also became the fuel that drove prices higher. Meanwhile, the stock market failed to absorb all the currency the bank kept issuing. The surplus far exceeded the real economy’s need for money, producing severe inflation.
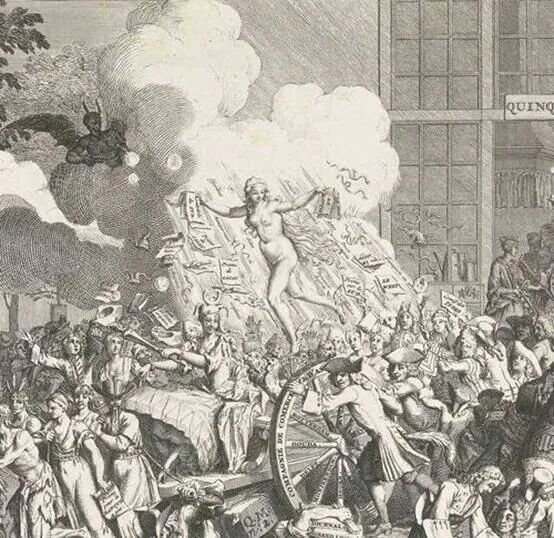
Eventually, holders began redeeming their banknotes more and more often. The bank had issued far too many notes, and the amount in circulation greatly exceeded its reserves. After several redemption attempts failed, panic began to spread. News also arrived from the Americas that the Mississippi River basin did not contain the abundant precious-metal deposits investors had been promised. Mississippi Company shares, already trading at extraordinary prices, began to fall and deepened the panic. People rushed to exchange their banknotes for coins, and the notes depreciated as the run intensified. Hoping to restore confidence, the French government issued three decrees around February 1720. It first devalued metal coins and then barred people from holding more than 500 livres in coin. Yet even as it imposed these measures, the government continued to expand the banknote supply. Distrust mounted, and people sought every possible way to cash out. By October 1720, the situation was beyond repair. The government abolished the banknotes and stripped the Mississippi Company of all its privileges. The stock-market bubble quickly burst, inflicting enormous losses on French society and its economy. Money had helped inflate the bubble; now it deepened the crisis. An oversupply of banknotes and the market crash destroyed confidence in paper currency, sending its value into a steep decline. Because the note supply far exceeded the bank’s reserves, redemption became increasingly difficult and the depreciation accelerated. As the banknotes collapsed, they pulled the wider economy down with them. Businesses and commercial ventures built on the vast money supply faced collapse and bankruptcy. With nowhere near enough coin to redeem all the notes, many ordinary people also saw their wealth evaporate.
After the frenzy, France entered a century-long period of distrust in finance and credit. This greatly slowed the development of its capitalist economy and gradually put France at a disadvantage in overseas colonization, giving Britain an opportunity to build the empire on which the sun never set. Later economists still regarded John Law as an important thinker of his age, but a close look at his work reveals many half-formed ideas and a limited understanding of the value and functions of money. Those weaknesses helped sow the seeds of the disaster he eventually orchestrated. A gambler opened a bank, rose to high office, and toyed with the wealth of an entire country. It is a remarkable spectacle. Law spent his final years in Venice. Many valuable works of art were reportedly found in his home after his death, suggesting that he remained quite comfortable in old age, although compared with his former glory, those possessions were probably a pittance. After he died, the French supplied him with a rather curious epitaph: “A famous Scotsman lies here,
His gift for arithmetic had no peer,
With simple rules of algebra,
He left all France gravely ill.”
References
- “Misleading Monetary Policy: The French Mississippi Bubble,” Jiang Lichang, Urban Finance; “Echoes of History: The Mississippi Bubble,” Amy Farber, Financial Market Research; “John Law: Child of the Storm, Born of Crisis,” Zhang Pingping, New Industrial Economy
- Images sourced from the internet
 爱发电(点击图片跳转)